A “realistic analysis” has shown that there is “no LNG supply glut” and if any surplus is experienced on the market, it will be “meagre” and the market should “rebalance”, said GECF secretary-general Yury Sentyurin.
“There is a recurrent narration and a common perspective among market players that the global LNG market would face a glut, which would persist till 2022. It makes sense when more than 115mn tonnes of LNG capacity are expected to come onstream between 2017 and 2022. Accordingly, there was a variety of forecasts on when this oversupply in the market is expected to end,” Sentyurin told Gulf Times in an interview.
As to what extent will these forecasts materialise, the GECF secretary-general said, “In fact, a reaction of market fundamentals is different from what was already forecasted and there is a need to wait and see how LNG supply and demand balance would take place in the coming years. The development of the LNG market in 2017 can be a good example.”
Despite the previously forecasted oversupply for the year 2017, global LNG trade reached 289mn tonnes, 10.3% higher compared to 2016. It means 27mn tonnes of additional LNG, which were mostly absorbed by the increase in demand driven by China and colder than normal weather in North East Asia.
Meanwhile, in 2017 the average price of spot LNG both in North East Asia and South West Europe markets increased by 25% and 30% respectively in comparison with 2016.
In fact, the market balanced both in higher quantity of traded volumes and level of prices. Consequently, in 2017, the glut was not observed in the LNG market as speculated.
Therefore, any realistic analysis on the subject of glut in LNG market needs to consider various aspects, Sentyurin noted.
First, projection about incremental capacity during the next five years could be tracked, as information about LNG plants are available and visible for most of market players (based on final investment decisions – FIDs). However, forecasting growth of demand is a difficult task that depends a lot on factors such as energy policies, prices, climate concerns and geopolitics.
The lack of FIDs for new LNG projects observed in the recent past, with only two FIDs taken in 2016 and one in 2017 (Coral FLNG of Mozambique), is an indicator of a probable supply shortage in the next five years.
Second, there is a difference between capacity, which is supposed to come on stream and supply of LNG volumes into the market because of the ramp of the projects and utilisation rates.
Third, an oversupply in the LNG market should result in lower prices. If the pretended oversupply by some forecasters combined with lower prices, has to happen and persist for a long period, the market could react through postponement of projects’ FIDs, lower plant utilisations.
Oversupply in the market, Sentyurin said, can be absorbed by Europe as a “sink market”, or new markets like China or South East Asia.
From the supply side, Sentyurin said, it makes sense that suppliers defer supplies by one or two years later through under-utilisation of plant and shut-in of projects as reaction to the market condition.
“It is certain that GECF member countries will be there at the appropriate time, with the adequate volumes to satisfy the global markets’ need based on ‘win-win’ situation,” Sentyurin noted.
The shipping fuel price and spot charter rates are forecasted to be stable and expected to stabilise shipping costs at the current level, according to GECF secretary-general Yury Sentyurin.
This, he said could “prevent shipping costs from skyrocketing” to the pre-2014 levels.
The global LNG capacity is expected to grow from 377mn tonnes per year (mtpy) in 2017 to around 463mtpy by 2020 mainly from new projects in the US, Australia and Russia.
Likewise, the global LNG trade is also forecasted to increase from 289mtpy in 2017 to 314mtpy and 353mtpy in 2018 and 2019 respectively, with strong growth in LNG imports from China and India, Sentyurin told Gulf Times.
Historically, he said LNG carriers and their capacity have grown in line with growing LNG trade and liquefaction capacity. In 2018 and 2019, a total of 73 new LNG carriers are expected to be commissioned (an increase from 467 vessels in 2017) with an overall capacity of 5.5mtpy (an increase from 32.8mtpy capacity in 2017).
“This is considered to be sufficient to meet the growing LNG trade. However, as only a small number of vessels are expected to be commissioned post 2019, amidst growing demand for spot LNG, this could lead to a shortfall in available LNG carriers from 2020,” Sentyurin noted.
There are several factors, which affects vessels availability for LNG trade, he pointed out.
Firstly, the duration of the charter contracts is of significant importance. The growing demand of short-term/spot LNG trade entails increasing demand for LNG vessels not operating under long-term contracts.
As of early 2018, 65% of the LNG carriers were chartered under long-term contracts valid until 2020 while the remaining 35% could be chartered under short-term or spot contracts.
Another factor is the seasonality demand for LNG, which is higher during the northern hemisphere winter and summer months and declines during spring and autumn months.
Finally, since new built LNG carriers are usually assigned to new LNG plants, delays in the commissioning of new LNG plants have led to some vessels coming to the market before the LNG plant is commissioned, he said.
LNG shipping costs, which consist of LNG carriers’ charter rates, shipping fuel prices and other costs such as port fees, canal fees and boil of gas, could represent up to 25% of the delivered LNG price depending on the trade route, Sentyurin said.
Charter rates, fuel price (which is highly dependent on the oil price due to the dominance of fuel oil in the bunkering fuel market) and the distance of trade routes have a significant impact on shipping costs.
He noted spot charter rates for LNG carriers, which averaged $28,000/day in 2017 declined from a high of $142,000/day in 2012 due to the growing number of LNG carriers and reinforcing competition in the market, but recorded a modest recovery from a low of $23,000/day in 2016.
Spot charter rates also fluctuate in line with the seasonal demand for LNG. The shipping fuel prices declined to $298/t in 2015 from $673/t in 2012 due to the lower oil prices and raised the competitiveness of long-haul trade routes and translated into a decline in LNG prices.
In March 2018, spot charter rates and fuel prices averaged $36,600/day and $384/t respectively. The shipping fuel price and spot charter rates are forecasted to be stable and is expected to stabilise shipping costs at the current level and could prevent shipping costs from skyrocketing to the pre-2014 levels.
GECF Secretariat currently monitors developments in the LNG shipping industry in correlation with LNG trade using its ‘Shipping Cost Model’, which was developed in-house, Sentyurin added.
Flannery narrows focus again in revamp of U.S. business icon
Company says it will maintain dividend through health spinoff
This is John Flannery’s General Electric Co. — and so far, Wall Street likes it.
A year after being named chief executive officer, Flannery took the boldest steps yet to revamp the sinking corporate titan, unveiling plans to pull GE out of the health-care and oil markets. By slimming it down and reorienting around power, renewable energy and aviation, he hopes to breathe new life into the 126-year-old company.
“We’re refashioning the company at every level,” Flannery said Tuesday in an interview. “It’s fundamentally positioning the company for the future.”
The overhaul will profoundly reshape an icon of American business –- albeit one that has fallen sharply from its Jack Welch-era heyday at the turn of the century. When Flannery’s done, GE will bear little resemblance to the conglomerate that once counted NBC, home-appliances, plastic, locomotives and a sprawling finance unit among its operations.
This is John Flannery’s General Electric Co. — and so far, Wall Street likes it.
A year after being named chief executive officer, Flannery took the boldest steps yet to revamp the sinking corporate titan, unveiling plans to pull GE out of the health-care and oil markets. By slimming it down and reorienting around power, renewable energy and aviation, he hopes to breathe new life into the 126-year-old company.
“We’re refashioning the company at every level,” Flannery said Tuesday in an interview. “It’s fundamentally positioning the company for the future.”
The overhaul will profoundly reshape an icon of American business –- albeit one that has fallen sharply from its Jack Welch-era heyday at the turn of the century. When Flannery’s done, GE will bear little resemblance to the conglomerate that once counted NBC, home-appliances, plastic, locomotives and a sprawling finance unit among its operations.
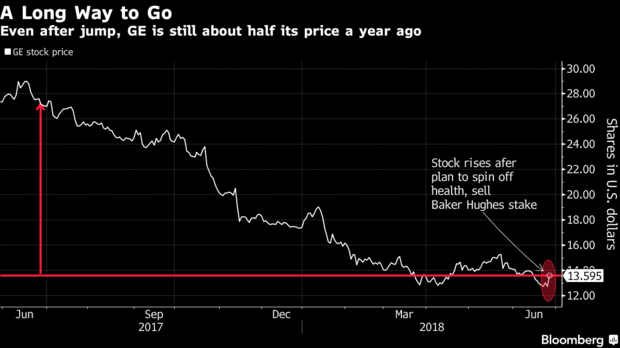
The new GE won an early embrace from investors. The shares surged 8.5 percent to $13.84 at 2:12 p.m. after advancing as much as 8.9 percent for the biggest intraday gain in three years.
The announcement clears away lingering concerns over GE’s debt while laying out a plan to monetize several major assets, said Nicholas Heymann, an analyst with William Blair & Co. The moves will also help GE weather the storm in the gas-power market until it begins to improve in a few years, he said.
“It’s the escape from the Alamo,” he said. “You’re basically reconfiguring the company to bring forward the value-creation opportunities.”
Still, as the Boston-based manufacturer struggles with cash flow issues and weak demand for equipment such as gas turbines, it’s far from recovered. GE fell 27 percent this year through Monday, following a 45 percent decline last year — a slump that led to GE’s removal [3]this week from the Dow Jones Industrial Average after more than 100 years.
Trian Applause
Trian Fund Management, which holds a stake in GE and has a seat on the board, said it welcomed the moves. “Trian supports the strategic initiatives announced today by GE and believes that these initiatives will create substantial value for shareholders,” the fund led by investor Nelson Peltz said in an emailed statement.
GE will narrow its focus to power, renewable energy and jet engines, according to a company statement. It will spin off its medical-equipment business and sell its majority stake in oilfield supplier Baker Hughes.
GE Gives Investors a Breakup. That’s a Start: Brooke Sutherland
“We have argued for the full breakup of GE and we pretty much have that – at least a realistic version of that,” Scott Davis, an analyst at Melius Research, said in a report. The health-care division is “a solid asset” and “what will remain at GE will largely be an aerospace business and a power business.”
GE plans to reduce net debt by about $25 billion by 2020. The company said it would maintain its dividend through the health spinoff. After that, GE “expects to adjust the GE dividend with a target dividend policy in line with industrial peers.”
Dividend Risk
Payouts in health care are typically lower, so the combined dividend between GE and the spinoff will probably be less than current levels, Flannery said. Investors have been bracing for a possible cut as GE’s condition has deteriorated. The CEO already reduced the payout in November, a painful blow to the many investors who have come to rely on the steady income.
“The dividend will likely be cut materially,” Steve Tusa, an analyst at JPMorgan Chase & Co., said in a note to clients. “This is also ultimately a de facto equity raise and dividend cut when all is said and done.”
But the dividend announcement may be a relief to some investors. The payout won’t disappear completely, and a potential cut will only happen in line with the move to spin off the health unit, Heymann said.
S&P Global Ratings put GE’s A rating on a negative credit watch, saying it expects to downgrade it one notch to four levels above junk when the health spinoff is completed. Moody’s Investors Service reaffirmed its comparable A2 rating and said the moves were a positive step for GE’s credit.
Board Switch
GE said Larry Culp would take over as lead director. Culp, a former Danaher Corp. CEO, joined the board earlier this year.
Flannery’s latest moves cap a strategic review he has been pursuing since taking the helm last year from Jeffrey Immelt, while effectively marking his second attempt to present a turnaround to investors. In November, Flannery unveiled changes including asset sales and a board overhaul, while saying the GE of the future would revolve around the energy, aviation and health-care markets.
More Power, Less Capital
GE Capital’s contribution to total revenue has disappeared in the last decade
That generated criticism from investors who called the steps insufficient, and the shares continued to fall. Early this year, after GE detailed worse-than-expected problems with insurance liabilities, Flannery promised to explore bigger changes, including a possible breakup.
Following Siemens
Since then, Flannery has agreed to unload GE’s century-old locomotive operations. On Monday, he announced the sale of an industrial-engine business to buyout firm Advent International. Immelt sold most of GE’s banking and consumer operations.
Under the plan unveiled Tuesday, GE will sell 20 percent of the health business and spin off the rest to its shareholders tax-free. The health business makes imaging machines and other hospital equipment.
The exit from health care mirrors a similar move by Siemens AG, the German industrial giant that’s dramatically simplified its conglomerate structure in recent years.
The Munich-based manufacturer, which competes with GE in areas such as power-generation and medical scanners, sold shares in its Healthineers subsidiary in March, marking the country’s second-biggest initial public offering in almost two decades.
Shrinking Finance
The U.S. and European manufacturing titans have historically tracked each other’s business closely, with close competition in power turbines, household appliances, medical devices and light bulbs. Siemens today is a far leaner business than it was a decade ago, having cut ties with some historic assets such as its communications business and the Osram light-bulb business.
GE plans to “materially shrink” the balance sheet of its finance arm, GE Capital, targeting the sale of $25 billion in energy and industrial finance assets by 2020. The company also is exploring options to reduce its insurance exposure. GE shocked investors this year with a $15 billion shortfall in insurance reserves. It also disclosed an accounting investigation by the U.S. Securities and Exchange Commission.
The exit from the Baker Hughes stake — to occur over the next two to three years — will end GE’s brief, rocky tenure in the oil and gas market.
GE began an aggressive expansion of its crude operations in 2007 with the $1.9 billion acquisition of equipment-maker Vetco Gray, building on a small set of assets. Over the next seven years, GE shelled out more than $10 billion on additional deals, buying companies such as Wellstream and Dresser.
Just as GE Oil & Gas was becoming one of the company’s most prominent businesses, the market collapsed. The price of crude plummeted more than 60 percent over 2014 and 2015. With demand down sharply, the division has weighed on GE’s financial results.
What’s more, GE’s oilfield offerings were still limited compared to its rivals, constraining growth in the event of a recovery. Under Immelt, GE agreed in 2016 to join forces with Baker Hughes, creating a more-formidable player with a robust product lineup that would be better able to compete with industry leader Schlumberger Ltd.
That didn’t last long. Flannery said shortly after taking over last year that GE would explore options to get out of its 62.5 percent stake, without committing to a formal exit plan.
India has announced plans to increase share of natural gas to 15% by 2020 from around 7% today.
The Gas Exporting Countries Forum, through its member coun- tries, remains committed to supply additional LNG to the Indian market to help the country achieve its goal of natural gas repre- senting 15% of the primary energy mix by 2020, says GECF secretary- general Yury Sentyurin.
India is emerging as key country for future natural gas imports as the government has announced plans to increase the share of natural gas to 15% by 2020 from around 7% today.
Asked what the Indian push towards LNG meant for GECF, Sentyurin said, “First of all, India as one of the fastest growing emerging markets, with economic growth about 7%, represents a huge promising future for gas demand in coming years.
“In addition, the fertiliser industry leads gas consumption in the country accounting for around 34% of total gas consumption. The fer- tiliser sector is of critical importance for the agricultural sector in India, which contributed to 17% of India’s GDP in the fi nancial year 2016-17.”
On whether GECF would play a leading role in helping India reach its natural gas target, the secretary-general said, “The target of the gov- ernment to reach a 15% share in the energy mix means a lot not only for GECF, but for India as an important country engaging in securing energy for its industry, as well as for natural gas. “This denotes a golden future for this golden source of energy, widely available with GECF member countries sitting on more than 70% of its proven reserves.”
Sentyurin provided Gulf Times with some key facts and fi gures on natural gas market in India. India, he said, imports natural gas in the form of LNG amidst grow- ing domestic gas demand and declining domestic gas production. GECF member countries have been a reliable supplier of LNG to India for more than a decade, since imports started in 2004. In 2017, GECF countries supplied more than 80% of India’s LNG im- ports, which includes supplies based on long-term contracts and spot LNG sales, he said.
As of the beginning of 2018, India has more than 20mn tonnes per year (mtpy) of LNG supply under long-term contracts with more than 40% from GECF countries. He said GECF members have also strengthened the partnership with India, where India opted to purchase additional volumes of LNG from GECF members, in addition to the renegotiation of two long-term LNG contracts with some GECF countries based on ‘win-win’ situation.
At the same time, Sentyurin noted renegotiations with other non- GECF suppliers did not reach the same results. “This solid historical partnership with India is an asset in both sides that continues to be strengthened, especially with more calls for natural gas by Indian consumers,” he said. “There are plenty of opportunities of co-operation with this impor- tant partner that could go above selling and buying gas and LNG, where we have seen the interest of India to invest in upstream and gas export projects in some GECF countries,” Sentyurin added.
The two talked together for nearly an hour in the official papal library in the Vatican’s Apostolic Palace, about twice as long as Francis usually spends with heads of state or government.
They discussed “protection of the environment, migration, and multilateral commitment to conflict prevention and resolution, especially in relation to disarmament,” a Vatican statement said.
They also spoke about prospects for resolving conflicts in the Middle East and Africa and the future of Europe, it said.
At the end of the private part of the audience, Macron gave Francis a rare copy of Georges Bernanos 1936 book “Diary of a Country Priest”.
“I’ve read this book many times and it has done me good. It is a book that I have always loved very much,” the pope told Macron, 40, who was accompanied in the public parts of the meeting by his wife Brigitte.
Francis gave Macron a medallion depicting Martin of Tours, a 4th century saint who is depicted cutting his cloak in half to give it to a beggar in winter.
“This means the vocation of those who govern is to help the poor. We are all poor,” Francis told Macron as he was giving him the medallion.
Macron earned himself the nickname “president of the rich” in France after scrapping a wealth tax and cutting a popular housing allowance in the first year of his mandate, hurting his popularity with the working class.
As Macron left the library, he and Francis exchanged a two-cheek kiss, another very unusual gesture between a pope and a visiting head of state.
The Vatican was expected to issue a statement later on the themes discussed during the private talks.
Two months ago, Macron called for stronger ties between the state and the Catholic Church, a move critics said blurred a line that has kept French government free of religious intervention for generations.
The issue is particularly sensitive in historically Catholic France, where matters of faith and state were separated by law in 1905 and which is now home to Europe’s largest Muslim and Jewish communities.
France’s guiding principles also hold that religious observance is a private matter, for all faiths.
Macron was raised in a non-religious family and was baptized a Roman Catholic at his own request when he was 12.
After leaving the Vatican he was installed as the “First and Only Honorary Canon” of the Rome Basilica of St John’s in Lateran, which is the pope’s cathedral in his capacity as bishop of Rome.
Under a tradition that began in the 15th century when France was a monarchy, French leaders are automatically given the title.
Macron took his seat of honor in basilica’s elaborately carved wooden choir stall to the applause of those in attendance, including members of the local French ex patriot community.
Additional reporting by Michel Rose in Paris, Editing by Richard Balmforth
Le chef de l’Etat français, qui sera accompagné par son épouse Brigitte, des ministres Gérard Collomb (Intérieur et Cultes) et Jean-Yves Le Drian (Affaires étrangères) est attendu à 10h au Saint-Siège pour un tête-à-tête qui devrait durer une trentaine de minutes.
Il s’entretiendra ensuite avec le cardinal, secrétaire d’Etat Monseigneur Pietro Parolin, qui sera également présent à un déjeuner à la villa Bonaparte, le siège de l’ambassade de France au Vatican, avant une rencontre avec la communauté française et une conférence de presse.
Un an après leur premier entretien téléphonique, Emmanuel Macron “aura à coeur de présenter au pape son approche transversale” sur la question migratoire, souligne l’Elysée, et insistera sur l’importance d’améliorer la réponse européenne, à quelques jours d’un Conseil européen qui s’annonce houleux.
Le pape, qui avait réservé l’un de ses premiers déplacements en 2013 à l’île italienne de Lampedusa, où il avait fustigé “l’indifférence” du monde à l’égard de migrants, n’a pas mâché ses mots ses cinq dernières années sur la gestion européenne des flux de migrants traversant la Méditerranée.
Dans une interview à Reuters la semaine dernière, François a notamment mis en garde l’Europe contre un “hiver démographique” si le continent se fermait aux migrants et dénoncé les “psychoses” alimentées selon lui par les populistes.
“PAS DE DIMENSION SPIRITUELLE”
La question des Chrétiens d’Orient, qui sera au coeur d’une mission qu’Emmanuel Macron entend lancer dans les prochains jours et qui devrait déboucher sur un rapport dans trois mois, sera également abordée. Celles du climat et de l’aide au développement pourraient également être évoqués.
Emmanuel Macron prendra symboliquement possession au cours d’une cérémonie de la stalle qui marque son titre de premier et unique chanoine d’honneur de la basilique Saint-Jean du Latran. Ce titre est remis de façon automatique aux dirigeants français en vertu d’une tradition qui remonte à Henri VI.
A l’exception de Georges Pompidou, de François Mitterrand et de François Hollande, tous les chefs d’Etat français de la Ve République depuis le Général de Gaulle en 1967 ont fait le déplacement à Rome pour prendre possession de ce titre.
Anticipant les potentielles critiques sur une atteinte à la laïcité, l’Elysée a insisté sur le fait que cette cérémonie n’avait “aucune dimension spirituelle mais une signification honorifique et historique”.
“Chanoine n’est pas un titre religieux mais laïc (…) il n’y a pas d’enjeu de laïcité”, a-t-on souligné, deux mois après le discours des Bernardins qui avait été bien perçu par les catholiques mais décrié par l’opposition comme une “atteinte sans précédent à la laïcité”.
Interpréter cette visite au pape “comme un nouveau pas en avant vers les catholiques paraît complètement abusif puisque chacun de ses prédécesseurs l’a fait”, a-t-on ajouté. Emmanuel Macron “a dit à maintes reprises qu’il était agnostique, il revendique sa formation jésuite, il revendique d’avoir été baptisé à 12 ans mais il revendique aussi aujourd’hui d’être en marge de l’Eglise”.
Etihad Airways, Abu Dhabi’s state airline, has offered its pilots a two-year secondment to Emirates, as the airlines pivot towards stronger collaboration, cut costs, streamline operations and address reports of pilot shortages in the industry.
“Such programmes enable airlines to effectively manage their pilot resources,” an Etihad spokesman said in an emailed statement to The National on Sunday.
“We are working with Etihad on a secondment programme for some of their pilots,” said a spokeswoman for Emirates. “This is a common practice in our industry which gives airlines more flexibility in managing their pilot resources.”
An internal letter dated June 21 circulating on the internet, which Etihad confirmed to The National as authentic, showed the airline had invited staff to submit non-binding expressions of interest for the secondment opportunity, ahead of a roadshow with Emirates’ recruitment team to be held at Etihad’s Abu Dhabi headquarters.
The proposed secondment would see selected Etihad pilots transferred to Emirates for two years, during which time they would be placed on a leave of absence from the Abu Dhabi airline, receive their salary and benefits as per an Emirates package, and retain their Etihad job ranking until their return.
Etihad employs about 2,220 pilots and a relatively small proportion of the total are expected to take up the opportunity. Emirates employs 4,157 pilots as of its 2017-2018 financial year. The changes come as Etihad continues a company-wide review that successfully narrowed losses by 22 per cent to $1.52 billion (Dh5.58bn) in 2017.
Last year, the airline withdrew its investments in troubled Air Berlin and Alitalia as well as halved the number of its equity holdings, and appointed a new chief executive. The airline has also scrapped unprofitable routes and slashed other costs.
Emirates and Etihad have said they are open to greater collaboration to improve efficiencies, for example in the fields of catering, ground handling and supply chain logistics.
“It’s fair to say that, as two partners from the UAE, we will continue to consider, where appropriate, what are the things that we can do together,” Etihad’s new group chief executive Tony Douglas told the Global Aerospace Summit in Abu Dhabi in April.
Pilot secondments “are something Etihad has done for several years with partner airlines around the world”, said the Etihad spokesmanon Sunday.
The airline began a pilot secondment programme in 2013 as part of international expansion plans, and in 2015 offered participants the option of transferring to permanent contracts. The programme was run with partners which at the time included Air Berlin, Alitalia, Darwin Airline, Jet Airways and others.
However, this is the first time Etihad has worked with Emirates in this way, and follows reports that the Dubai airline is looking to plug a shortfall of at least 150 pilots.
Emirates has played down such reports, with its president, Tim Clark, saying in May the airline is “a tad short of pilots but should be alright in September or October”.
Analysts said secondments are a clever way for airlines to reduce costs without losing staff in the long term, as they can recall staff when finances improve.
“In offering opportunities at Emirates, not only does Etihad temporarily offload some of its costs and pilots, but Emirates gains extra fully qualified flight deck staff a lot quicker than planned,” said Saj Ahmad, chief analyst at Strategic Aero Research.
Siddhartha Sharma, president and chief executive of analyst company Interglobe Air Transport, said the two airlines’ standard operating procedures are different: “It’s like the same cars operated by different humans under different umbrellas.” He said pilots would have to evaluate the potential benefits of a move.
ATHENS (Reuters) – Greece’s largest carrier Aegean Airlines (AGNr.AT) signed a $5 billion deal with Airbus (AIR.PA) for up to 42 aircraft to renew its fleet of single-aisle planes, stay competitive and add capacity for future expansion.
It is the largest order by a Greek carrier and third time Aegean has invested in new aircraft since launching operations 19 years ago.
Seeking to reduce maintenance and fuel costs, Aegean, a member of the Star Alliance airline group, had been considering the Airbus A320neo or Boeing’s (BA.N) 737 MAX. It picked Airbus in late March.
“I believe it is a good day for Greece with the news coming out of Brussels, but certainly a very good day for Aegean and Airbus,” Airbus CEO Tom Enders said at a signing ceremony at Aegean’s technical base at Athens airport.
Earlier on Friday Greece reached an agreement with euro zone finance ministers, securing debt relief to smooth out its return to market financing after eight years of living mainly on loans from euro zone states.
“We begin a new cycle of growth while reducing our operating cost, necessary in a globalised and competitive market,” said Dimitris Gerogiannis, Aegean’s CEO, adding the order was for up to 42 planes, including 10 A321s.
Aegean, which flies domestic and international routes, also owns former flag carrier Olympic Airlines, which was privatized in 2013. Most of its current leases need to be replaced between 2019 and 2023.
Last year, Aegean grew full-year net earnings by 87 percent on an improved load factor and higher sales, riding a strong tourism year. In 2017 it flew a total of 13.2 million passengers.
While the new aircraft will offer 15 percent fuel savings, they are just the hardware, CEO Gerogiannis said. “It is the quality, culture and efficiency of our people that gives us our competitive advantage,” he said.
Aegean executives said the carrier will also invest 30 million euros ($35 million) to build a new 12,000 square meter facility in Athens for flight and cabin crew training.
Reporting by George Georgiopoulos; Editing by Keith Weir
ATHENS: Greek Prime Minister Alexis Tsipras said Friday his country was “turning a page” after eurozone ministers declared its crisis over as they granted Athens debt relief under a bailout exit strategy.
The eurozone ministers’ agreement comes nearly a decade after Athens finances spun out of control, sparking three bailouts and threatening the country’s euro membership.
“Yesterday we reached a historic agreement on Greece’s debt with the Eurogroup,” Tsipras told the country’s president, Prokopis Pavlopoulos.
“We are turning a page,” he said, adding that Greece had to remain on the path of reform.
Tsipras, who hates ties and hasn’t worn one since becoming prime minister in 2015, had pledged at the time he would wear one “only when (Greece’s) debt is cut.”
He honoured his pledge late Friday, arriving at a celebratory meeting of his coalition lawmakers sporting a maroon-coloured tie with a white shirt and blue jacket.
He removed it however at the end of a speech to the gathering, observing that “the Greek people had won a battle but not the war” and promising to continue to lead the fight” to victory.
Following the eurozone ministers’ hard-fought agreement declared earlier Friday, Greece is slated to leave its third financial rescue since 2010 on Aug. 20.
“The Greek crisis ends here tonight,” said EU Economic Affairs Commissioner Pierre Moscovici, after the marathon talks in Luxembourg.
The deal was expected to be an easy one, but last-minute resistance by Germany – Greece’s long bailout nemesis and biggest creditor – dragged the talks on for six hours.
The ministers agreed to extend maturities by 10 years on major parts of its total debt obligations, a mountain that has reached close to double the country’s annual economic output.
They also agreed to disburse 15 billion euros ($17.5 billion) to ease Greece’s exit from the rescue programme.
This would leave Greece with a hefty 24 billion euro safety cushion, officials said.
“The agreed debt relief is bigger than we had expected,” Citi European Economics said in a note.
“In particular, the 10-year extension of the EFSF loans’ maturity and most importantly the grace period on interest payments is a significant development,” they added.
“The Greek government is happy with the agreement,” Greek Finance Minister Euclid Tsakalotos said after the talks.
But “to make this worthwhile we have to make sure that the Greek people must quickly see concrete results… they need to feel the change in their own pockets,” he added.
Tsakalotos’ predecessor in the government, maverick economist Yanis Varoufakis, was more scathing in his assessment.
“Congratulations, comrades. [Eurozone creditors] extend the Greek state’s bankruptcy into 2060 and they call it debt … relief,” he tweeted.
The eight-year crisis toppled four governments and shrank the economy by 25 percent. Unemployment soared and still hovers over 20 percent, sending thousands of young educated Greeks abroad.
Optimism is tempered by Greece’s remaining fiscal obligations, which will demand serious discipline, observers say.
“This is a very tight programme. A surplus of 3.5 percent to 2022 and 2.2 percent (on average) to 2060 is not easy at all,” Kostas Boukas, asset management director at Beta Securities, told Athens 9,84 radio.
“We’ll have to see if the pledges will be kept, especially as they depend on international developments as well,” he said.
Under pressure from its creditors, Greece has already agreed to slash pensions again in 2019, and reduce the tax-free income threshold for millions of people in 2020.
Further cuts will be made to maintain the 3.5-percent surplus, if necessary.
“It would be a terrible mistake to cultivate illusions that the end of the bailout means a return to normality,” said pro-opposition daily Ta Nea.
“What follows is tough oversight which no other country has experienced in a post-bailout period,” the daily said.
The European Commission has already specified that Greece will remain under fiscal supervision until it repays 75 percent of its loans.
Athens has received 273.7 billion euros in assistance since 2010, enabling it to avoid punishing borrowing rates on debt markets.
The International Monetary Fund, led by the tough-talking Christine Lagarde, welcomed the debt relief, but cited reservations about Greece’s obligations over the long term.
“In the medium term analysis there is no doubt in our minds that Greece will be able to reaccess the markets,” Lagarde said after the talks.
“As far as the longer term is concerned we have concerns,” she added.
The reform-pushing IMF played an active role in the two first Greek bailouts, but took only an observer role in the third in the belief that Greece’s debt pile was unsustainable in the long term.
French President Emmanuel Macron also hailed the “very positive” agreement, saying it showed that “Europe is moving forward” despite recent difficulties.
Copyrights 2018, The Daily Star – All Rights Reserved
Major oil producers have agreed to pump more crude to help reduce prices and prevent a supply shortage, in a significant reversal of Opec’s strategy of curbing output over the past 18 months.
After a fraught meeting in Vienna in which Iran was initially at odds with a Saudi-led drive to boost production, ministers settled on a target they said would increase output by around 1m barrels per day (bpd).
Donald Trump, who has blamed the cartel for recent oil price highs, appeared to welcome the deal. “Hope Opec will increase output substantially. Need to keep prices down!” the US president tweeted after the agreement.
However, analysts and ministers said the actual amount of extra oil is likely to be around a third lower than the headline 1m figure.
Joe McMonigle, an energy analyst at HedgeEye, said: “I suspect we will eventually get some calculations from Opec but [the] lack of details is bullish not bearish for oil prices.”
Brent crude, the international benchmark, was up nearly 2% to $74.47 (£56.12) a barrel, shortly after the agreement was announced. It hit $80 a barrel last month before falling back.
The oil cartel also failed to spell out how the extra production would be allocated among members, a key question as several have no capacity to pump more crude.
Friday’s deal centres on how closely countries have stuck to production cuts that have been in effect since the start of 2017, driving a recovery in oil prices.
Opec said the cuts of 1.2m bpd had been far exceeded – at 158% in May – so in Vienna the group agreed to target 100% compliance instead. That would equate to an effective increase of around 1m bpd.
Roger Diwan, a veteran Opec observer and analyst at IHS Markit, said: “That’s a fudge for sure.”
He said the agreement paved the way for the Saudis to pump more, while the Iranians could sell the deal domestically by saying they had blocked a bigger increase.
Khalid al-Falih, the Saudi energy minister, said the kingdom was ready to increase production.
“Saudi Arabia is unique. All of our spare capacity is available at short notice,” he said. However, he said the impact of the increase would not be felt until the end of summer, because crude would take weeks to reach markets.
The minister acknowledged that not all of the cartel’s members were in a position to increase output.
Crisis-hit Venezuela has suffered a nosedive in production, while Iran’s exports are due to be hit by US sanctions, so neither are in a position to increase supplies.
Iran failed in its effort to shoehorn a coded criticism of the US into the Opec communique.
Suhail al-Mazroui, the UAE energy minister and meeting’s president, suggested the agreement represented a good compromise.
“I think for the group to agree that we target that collective 1.2[m bpd] level is something that is good for us. That takes into account the differences between the different countries,” he said.
After nearly two years of relative unity at Opec as the group cut production to rebalance supply and demand, the talks in Vienna this week found the cartel divided.
After arriving on Tuesday, Iranian oil minister Bijan Zanganeh threatened to veto any agreement to raise output, though he eventually reached agreement with his Saudi counterpart on Friday. Observers had said earlier in the week that, “the body language has been awful”.
The Ecuadorean oil minister, Carlos Pérez, when asked if the talks had been fractious, said: “It’s been a difficult situation.” But he added the cartel hoped to continue its unity despite the disagreements.


 By Rick Clough