Etihad Airways, Abu Dhabi’s state airline, has offered its pilots a two-year secondment to Emirates, as the airlines pivot towards stronger collaboration, cut costs, streamline operations and address reports of pilot shortages in the industry.
“Such programmes enable airlines to effectively manage their pilot resources,” an Etihad spokesman said in an emailed statement to The National on Sunday.
“We are working with Etihad on a secondment programme for some of their pilots,” said a spokeswoman for Emirates. “This is a common practice in our industry which gives airlines more flexibility in managing their pilot resources.”
An internal letter dated June 21 circulating on the internet, which Etihad confirmed to The National as authentic, showed the airline had invited staff to submit non-binding expressions of interest for the secondment opportunity, ahead of a roadshow with Emirates’ recruitment team to be held at Etihad’s Abu Dhabi headquarters.
The proposed secondment would see selected Etihad pilots transferred to Emirates for two years, during which time they would be placed on a leave of absence from the Abu Dhabi airline, receive their salary and benefits as per an Emirates package, and retain their Etihad job ranking until their return.
Etihad employs about 2,220 pilots and a relatively small proportion of the total are expected to take up the opportunity. Emirates employs 4,157 pilots as of its 2017-2018 financial year. The changes come as Etihad continues a company-wide review that successfully narrowed losses by 22 per cent to $1.52 billion (Dh5.58bn) in 2017.
Last year, the airline withdrew its investments in troubled Air Berlin and Alitalia as well as halved the number of its equity holdings, and appointed a new chief executive. The airline has also scrapped unprofitable routes and slashed other costs.
Emirates and Etihad have said they are open to greater collaboration to improve efficiencies, for example in the fields of catering, ground handling and supply chain logistics.
“It’s fair to say that, as two partners from the UAE, we will continue to consider, where appropriate, what are the things that we can do together,” Etihad’s new group chief executive Tony Douglas told the Global Aerospace Summit in Abu Dhabi in April.
Pilot secondments “are something Etihad has done for several years with partner airlines around the world”, said the Etihad spokesmanon Sunday.
The airline began a pilot secondment programme in 2013 as part of international expansion plans, and in 2015 offered participants the option of transferring to permanent contracts. The programme was run with partners which at the time included Air Berlin, Alitalia, Darwin Airline, Jet Airways and others.
However, this is the first time Etihad has worked with Emirates in this way, and follows reports that the Dubai airline is looking to plug a shortfall of at least 150 pilots.
Emirates has played down such reports, with its president, Tim Clark, saying in May the airline is “a tad short of pilots but should be alright in September or October”.
Analysts said secondments are a clever way for airlines to reduce costs without losing staff in the long term, as they can recall staff when finances improve.
“In offering opportunities at Emirates, not only does Etihad temporarily offload some of its costs and pilots, but Emirates gains extra fully qualified flight deck staff a lot quicker than planned,” said Saj Ahmad, chief analyst at Strategic Aero Research.
Siddhartha Sharma, president and chief executive of analyst company Interglobe Air Transport, said the two airlines’ standard operating procedures are different: “It’s like the same cars operated by different humans under different umbrellas.” He said pilots would have to evaluate the potential benefits of a move.
ATHENS (Reuters) – Greece’s largest carrier Aegean Airlines (AGNr.AT) signed a $5 billion deal with Airbus (AIR.PA) for up to 42 aircraft to renew its fleet of single-aisle planes, stay competitive and add capacity for future expansion.
It is the largest order by a Greek carrier and third time Aegean has invested in new aircraft since launching operations 19 years ago.
Seeking to reduce maintenance and fuel costs, Aegean, a member of the Star Alliance airline group, had been considering the Airbus A320neo or Boeing’s (BA.N) 737 MAX. It picked Airbus in late March.
“I believe it is a good day for Greece with the news coming out of Brussels, but certainly a very good day for Aegean and Airbus,” Airbus CEO Tom Enders said at a signing ceremony at Aegean’s technical base at Athens airport.
Earlier on Friday Greece reached an agreement with euro zone finance ministers, securing debt relief to smooth out its return to market financing after eight years of living mainly on loans from euro zone states.
“We begin a new cycle of growth while reducing our operating cost, necessary in a globalised and competitive market,” said Dimitris Gerogiannis, Aegean’s CEO, adding the order was for up to 42 planes, including 10 A321s.
Aegean, which flies domestic and international routes, also owns former flag carrier Olympic Airlines, which was privatized in 2013. Most of its current leases need to be replaced between 2019 and 2023.
Last year, Aegean grew full-year net earnings by 87 percent on an improved load factor and higher sales, riding a strong tourism year. In 2017 it flew a total of 13.2 million passengers.
While the new aircraft will offer 15 percent fuel savings, they are just the hardware, CEO Gerogiannis said. “It is the quality, culture and efficiency of our people that gives us our competitive advantage,” he said.
Aegean executives said the carrier will also invest 30 million euros ($35 million) to build a new 12,000 square meter facility in Athens for flight and cabin crew training.
Reporting by George Georgiopoulos; Editing by Keith Weir
ATHENS: Greek Prime Minister Alexis Tsipras said Friday his country was “turning a page” after eurozone ministers declared its crisis over as they granted Athens debt relief under a bailout exit strategy.
The eurozone ministers’ agreement comes nearly a decade after Athens finances spun out of control, sparking three bailouts and threatening the country’s euro membership.
“Yesterday we reached a historic agreement on Greece’s debt with the Eurogroup,” Tsipras told the country’s president, Prokopis Pavlopoulos.
“We are turning a page,” he said, adding that Greece had to remain on the path of reform.
Tsipras, who hates ties and hasn’t worn one since becoming prime minister in 2015, had pledged at the time he would wear one “only when (Greece’s) debt is cut.”
He honoured his pledge late Friday, arriving at a celebratory meeting of his coalition lawmakers sporting a maroon-coloured tie with a white shirt and blue jacket.
He removed it however at the end of a speech to the gathering, observing that “the Greek people had won a battle but not the war” and promising to continue to lead the fight” to victory.
Following the eurozone ministers’ hard-fought agreement declared earlier Friday, Greece is slated to leave its third financial rescue since 2010 on Aug. 20.
“The Greek crisis ends here tonight,” said EU Economic Affairs Commissioner Pierre Moscovici, after the marathon talks in Luxembourg.
The deal was expected to be an easy one, but last-minute resistance by Germany – Greece’s long bailout nemesis and biggest creditor – dragged the talks on for six hours.
The ministers agreed to extend maturities by 10 years on major parts of its total debt obligations, a mountain that has reached close to double the country’s annual economic output.
They also agreed to disburse 15 billion euros ($17.5 billion) to ease Greece’s exit from the rescue programme.
This would leave Greece with a hefty 24 billion euro safety cushion, officials said.
“The agreed debt relief is bigger than we had expected,” Citi European Economics said in a note.
“In particular, the 10-year extension of the EFSF loans’ maturity and most importantly the grace period on interest payments is a significant development,” they added.
“The Greek government is happy with the agreement,” Greek Finance Minister Euclid Tsakalotos said after the talks.
But “to make this worthwhile we have to make sure that the Greek people must quickly see concrete results… they need to feel the change in their own pockets,” he added.
Tsakalotos’ predecessor in the government, maverick economist Yanis Varoufakis, was more scathing in his assessment.
“Congratulations, comrades. [Eurozone creditors] extend the Greek state’s bankruptcy into 2060 and they call it debt … relief,” he tweeted.
The eight-year crisis toppled four governments and shrank the economy by 25 percent. Unemployment soared and still hovers over 20 percent, sending thousands of young educated Greeks abroad.
Optimism is tempered by Greece’s remaining fiscal obligations, which will demand serious discipline, observers say.
“This is a very tight programme. A surplus of 3.5 percent to 2022 and 2.2 percent (on average) to 2060 is not easy at all,” Kostas Boukas, asset management director at Beta Securities, told Athens 9,84 radio.
“We’ll have to see if the pledges will be kept, especially as they depend on international developments as well,” he said.
Under pressure from its creditors, Greece has already agreed to slash pensions again in 2019, and reduce the tax-free income threshold for millions of people in 2020.
Further cuts will be made to maintain the 3.5-percent surplus, if necessary.
“It would be a terrible mistake to cultivate illusions that the end of the bailout means a return to normality,” said pro-opposition daily Ta Nea.
“What follows is tough oversight which no other country has experienced in a post-bailout period,” the daily said.
The European Commission has already specified that Greece will remain under fiscal supervision until it repays 75 percent of its loans.
Athens has received 273.7 billion euros in assistance since 2010, enabling it to avoid punishing borrowing rates on debt markets.
The International Monetary Fund, led by the tough-talking Christine Lagarde, welcomed the debt relief, but cited reservations about Greece’s obligations over the long term.
“In the medium term analysis there is no doubt in our minds that Greece will be able to reaccess the markets,” Lagarde said after the talks.
“As far as the longer term is concerned we have concerns,” she added.
The reform-pushing IMF played an active role in the two first Greek bailouts, but took only an observer role in the third in the belief that Greece’s debt pile was unsustainable in the long term.
French President Emmanuel Macron also hailed the “very positive” agreement, saying it showed that “Europe is moving forward” despite recent difficulties.
Copyrights 2018, The Daily Star – All Rights Reserved
Major oil producers have agreed to pump more crude to help reduce prices and prevent a supply shortage, in a significant reversal of Opec’s strategy of curbing output over the past 18 months.
After a fraught meeting in Vienna in which Iran was initially at odds with a Saudi-led drive to boost production, ministers settled on a target they said would increase output by around 1m barrels per day (bpd).
Donald Trump, who has blamed the cartel for recent oil price highs, appeared to welcome the deal. “Hope Opec will increase output substantially. Need to keep prices down!” the US president tweeted after the agreement.
However, analysts and ministers said the actual amount of extra oil is likely to be around a third lower than the headline 1m figure.
Joe McMonigle, an energy analyst at HedgeEye, said: “I suspect we will eventually get some calculations from Opec but [the] lack of details is bullish not bearish for oil prices.”
Brent crude, the international benchmark, was up nearly 2% to $74.47 (£56.12) a barrel, shortly after the agreement was announced. It hit $80 a barrel last month before falling back.
The oil cartel also failed to spell out how the extra production would be allocated among members, a key question as several have no capacity to pump more crude.
Friday’s deal centres on how closely countries have stuck to production cuts that have been in effect since the start of 2017, driving a recovery in oil prices.
Opec said the cuts of 1.2m bpd had been far exceeded – at 158% in May – so in Vienna the group agreed to target 100% compliance instead. That would equate to an effective increase of around 1m bpd.
Roger Diwan, a veteran Opec observer and analyst at IHS Markit, said: “That’s a fudge for sure.”
He said the agreement paved the way for the Saudis to pump more, while the Iranians could sell the deal domestically by saying they had blocked a bigger increase.
Khalid al-Falih, the Saudi energy minister, said the kingdom was ready to increase production.
“Saudi Arabia is unique. All of our spare capacity is available at short notice,” he said. However, he said the impact of the increase would not be felt until the end of summer, because crude would take weeks to reach markets.
The minister acknowledged that not all of the cartel’s members were in a position to increase output.
Crisis-hit Venezuela has suffered a nosedive in production, while Iran’s exports are due to be hit by US sanctions, so neither are in a position to increase supplies.
Iran failed in its effort to shoehorn a coded criticism of the US into the Opec communique.
Suhail al-Mazroui, the UAE energy minister and meeting’s president, suggested the agreement represented a good compromise.
“I think for the group to agree that we target that collective 1.2[m bpd] level is something that is good for us. That takes into account the differences between the different countries,” he said.
After nearly two years of relative unity at Opec as the group cut production to rebalance supply and demand, the talks in Vienna this week found the cartel divided.
After arriving on Tuesday, Iranian oil minister Bijan Zanganeh threatened to veto any agreement to raise output, though he eventually reached agreement with his Saudi counterpart on Friday. Observers had said earlier in the week that, “the body language has been awful”.
The Ecuadorean oil minister, Carlos Pérez, when asked if the talks had been fractious, said: “It’s been a difficult situation.” But he added the cartel hoped to continue its unity despite the disagreements.
The S-400 has never been used in combat, but it’s already causing geopolitical turmoil.
By Henry Meyer and Ilya Arkhipov
Russia’s S-400 missile system has never been used in combat. Yet it’s already provoking fights around the world, as Russia searches for buyers in markets long dominated by American weapons makers. China’s neighbors are fretting as the country bolsters its military reach with Russian hardware, encouraging India to follow suit. Tensions between rivals Saudi Arabia and Qatar have ratcheted up as both countries negotiate with Moscow on possible deals, while the recent decision by NATO member Turkey to buy the S-400 has drawn threats of U.S. sanctions.
With Algeria, Belarus, Iran, and Vietnam also likely customers, Russia could generate $30 billion in sales over the next 12 to 15 years, according to the Moscow Defense Brief, a leading publisher of Russian military information. That’s all part of President Vladimir Putin’s plan to use the Russian weapons industry not only to earn billions of dollars but also to drive a wedge between the U.S. and some of its key allies. “The S-400 has both commercial and geopolitical dimensions,” says Vladimir Frolov, a former Russian diplomat who’s now a foreign policy analyst in Moscow. “It creates an opening for Russian influence for years to come.”
The Russian weapon has a few advantages over the only other comparable missile system on the market, the MIM-104 Patriot, made by U.S. company Raytheon Co., according to defense research group Jane’s by IHS Markit Ltd. Both are surface-to-air systems designed to shoot down aircraft and ballistic missiles. But the S-400 has a longer range than the Patriot, 250 kilometers (155 miles) vs. 160 kilometers. An upgrade coming later this year is expected to stretch the S-400’s range to 400 kilometers. It also has a more powerful radar, can destroy targets moving twice as fast, and is quicker to set up. While both systems are mounted on trucks, the S-400 can be ready for action in five minutes, compared with an hour for a Patriot battery. The S-400 is also slightly cheaper than the Patriot, on a per-battery basis.
The S-500, an advanced version comparable to the U.S. Thaad anti-ballistic-missile system that’s capable of downing hypersonic cruise missiles, is expected to enter production by 2022. The S-400 is manufactured by the state-run company Almaz-Antey, which has been sanctioned by the U.S. over Russia’s military support for separatists in eastern Ukraine. Despite that, Almaz-Antey is opening two sites elsewhere in Russia to supplement its Moscow plant. The Russians don’t shy away from talking up the S-400 to potential buyers. It “has no equal,” says state arms trader Rosoboronexport’s spokesman Vyacheslav Davidenko. “Russian air-defense systems don’t allow anyone to attack without paying a price.”
The Patriot has superior anti-ballistic-missile capability, says Omar Lamrani, senior military analyst at Stratfor Enterprises LLC, a Texas consultant. It can also be integrated into other U.S.-made missile-defense systems, increasing its effectiveness. The Patriot has a long and successful track record on the battlefield, having come to fame during the 1991 Gulf War. But its performance recently has come under scrutiny. In March video footage appeared to show a failed Patriot launch as Saudi Arabia intercepted a barrage of rockets fired by Yemen’s Houthi rebels. One missile did an abrupt U-turn and crashed into the ground in the Saudi capital, and another one exploded midair. It’s unclear whether the Patriots malfunctioned or the Saudi crew failed to operate them properly. Whatever the cause, it hasn’t stopped Romania, Poland, and Sweden from pursuing plans to buy them. Raytheon declined to comment on the misfire footage, and says that the Patriot’s “performance in testing scenarios and in combat speaks for itself.”
Russia has a history of producing strong air-defense systems, dating to the Cold War, when it needed to counter NATO’s air forces. In the early 1990s the U.S. paid Boris Yeltsin’s cash-strapped government $120 million for an air-defense launch complex to study the technology. Now the U.S. faces a growing threat from the sale of Russian advanced weaponry to its strategic rivals and erstwhile allies.
In 2014, China signed a $1.9 billion deal to buy 32 S-400 launchers, each equipped with four missiles, half of which were delivered last year, the Moscow Defense Brief says. New contracts with China may be in the pipeline, it adds; these acquisitions will allow the country to threaten aircraft in Taiwan, which Beijing regards as a rebel province, as well as challenge Japan and neighbors in Southeast Asia for control of the skies in disputed areas. “It poses big challenges for the U.S., Taiwan—which it is obliged to protect—also for American allies and anybody who challenges Chinese territorial claims in the South China Seas,” says Alexander Gabuev, chairman of the Carnegie Moscow Center’s Russia in the Asia-Pacific Program.
India, which has had sporadic skirmishes with China since the countries fought a bloody border war in 1962, is in the final stages of negotiating a $6 billion S-400 deal. According to Indian media, the contract may be signed before an October summit between Putin and Prime Minister Narendra Modi.
Turkey risks U.S. sanctions over its $2.5 billion deal, financed with Russian loans, to buy the S-400. Under a 2017 law, the White House has to penalize countries that conduct a “significant transaction” with Russia’s defense sector. A defense spending bill passed by the U.S. Senate on June 18 calls for a freeze in arms sales to Turkey in response to its S-400 purchases. The bill also calls for the removal of Turkey from the F-35 joint strike fighter program, a multicountry, $400 billion plan to build and sell tactical jets to allies. Turkey was a key member of the program; it had ordered 100 F-35s and was slated to co-produce the jet. Some of its companies are the sole producers of essential parts in the supply chain. “The Turks have got to decide whether they’re going to be in NATO or aligned with Russia,” says Senator James Lankford, an Oklahoma Republican.
Despite the threats, Turkey’s foreign minister, Mevlut Cavusoglu, says the deal to buy the S-400 is done. On June 13, Turkish President Recep Tayyip Erdogan said Turkey and Russia may also co-produce the next-generation S-500. “Russia seems to have communicated to Turkey that it’s in their interest in one way or another to align with them,” says Thomas Karako, director of the Missile Defense Project at the Center for Strategic & International Studies. “This is one of several ways in which they seem to be hugging their friends to the northeast.” The deal is a major milestone toward improving ties between the two countries after Turkey shot down a Russian fighter jet near its border with Syria in 2015.
On June 21, the U.S. Senate Committee on Appropriations passed an amendment attached to the annual Department of State funding bill that prohibits spending money to transfer the F-35 to Turkey until the secretary of state certifies that Turkey isn’t buying the S-400. “This provision makes it clear that if Turkey ignores the concerns of its NATO allies and moves forward with this partnership with Putin, it will no longer receive F-35s,” Senator Chris Van Hollen, a Democrat from Maryland, said in a statement.
Although losing Turkey as a customer would be a hit to F-35 manufacturer Lockheed Martin Corp., there are concerns that Russia will gain valuable intelligence—insights into U.S. air defense and aerial capabilities—if the country remains in the program. Senior U.S. defense officials have said that if Turkey operates both the F-35 and the S-400, it could compromise the F-35’s security, including its stealth capabilities. “It is in the American national interest to see Turkey remain strategically and politically aligned with the West, and we believe it is also in Turkey’s interests,” Assistant Secretary A. Wess Mitchell said at a congressional hearing in April.
As for Saudi Arabia, the increasingly warm ties it’s enjoyed with Russia, particularly over coordination in the oil markets, have also provoked alarm in the U.S. President Trump’s nominee for assistant secretary of state for near eastern affairs, David Schenker, said during his Senate confirmation hearing on June 14 that he would “tell Saudi Arabia not to do it” when asked about the kingdom’s talks to buy the S-400. During an historic visit by King Salman to Russia in October, Saudi Arabia agreed on other arms purchases, including antitank weapons and multiple-rocket launchers, and licensed Saudi production of Kalashnikov assault rifles.
Neighboring U.S.-allied states Kuwait, Bahrain, and the United Arab Emirates are also acquiring Russian weapons. The advanced Russian missile system has turned into a major bargaining chip in the region as rival powers seek to cement new relations with Russia to balance U.S. influence. In a letter to the French president, Saudi Arabia warned of “military actions” against Qatar if it buys the S-400, as Le Monde reported in early June.
The S-400 still has an element of “hype,” says Stratfor’s Lamrani. Still, “it has a very promising future—there are places where opportunities are opening up for Russia.” —With Stepan Kravchenko, Daniel Flatley, and Erik Wasson.
VIENNA (Reuters) – OPEC agreed with Russia and other oil-producing allies on Saturday to raise output from July, with Saudi Arabia pledging a “measurable” supply boost but giving no specific numbers.
The Organization of the Petroleum Exporting Countries had announced an OPEC-only production agreement on Friday, also without clear output targets. Benchmark Brent oil rose by $2.5 or 3.4 percent on the day to $75.55 a barrel.
On Saturday, non-OPEC oil producers agreed to participate in the pact but a communique issued after their talks with the Vienna-based group provided no concrete numbers amid deep disagreements between OPEC arch-rivals Saudi Arabia and Iran.
U.S. President Donald Trump was among those wondering how much more oil OPEC would deliver. “Hope OPEC will increase output substantially. Need to keep prices down!” Trump wrote on Twitter after OPEC announced its Friday decision.
The United States, China and India had urged oil producers to release more supply to prevent an oil deficit that could undermine global economic growth.
OPEC and non-OPEC said in their statement that they would raise supply by returning to 100 percent compliance with previously agreed output cuts, after months of underproduction.
Saudi Energy Minister Khalid al-Falih said OPEC and non-OPEC combined would pump roughly an extra 1 million barrels per day (bpd) in coming months, equal to 1 percent of global supply.
Top global exporter Saudi Arabia will increase output by hundreds of thousands of barrels, he said, with exact figures to be decided later.
“We already mobilized the Aramco machinery, before coming to Vienna, pre-empting this meeting,” Falih said, referring to the Saudi state oil company.
Russian Energy Minister Alexander Novak said his country would add 200,000 bpd in the second half of this year.
Asked to what extent the decision to increase supply had been driven by pressure from Trump, Novak said: “It is obvious that we are not being driven by tweets but base our actions on deep market analysis.”
IRAN, SAUDI DISAGREEMENT
Iran, OPEC’s third-largest producer, had demanded OPEC reject calls from Trump for an increase in oil supply, arguing that he had contributed to a recent rise in prices by imposing sanctions on Iran and fellow member Venezuela.
Trump slapped fresh sanctions on Tehran in May and market watchers expect Iran’s output to drop by a third by the end of 2018. That means the country has little to gain from a deal to raise output, unlike Saudi Arabia.
Iranian Oil Minister Bijan Zanganeh said the real increase could amount to as little as 500,000 bpd because Saudi Arabia would not be allowed to pump more on behalf of Venezuela, where output has collapsed in recent months.
“Each country which has produced less (than its allocation) can produce more. Those which cannot, will not… This means that Saudi Arabia can increase its production by less than 100,000 bpd,” Zanganeh told Argus Media.
But Falih said pro-rata quota reallocations did not have to be strict, meaning Saudi wanted to fill the gaps left by others.
“Some of the countries … are not going to be able to produce, so the others will. And that implies there will be indirectly a reallocation,” Falih said.
He also said OPEC could hold an extraordinary meeting before its next formal talks due on Dec. 3 or adjust deliveries in September, when its monitoring committee meets, if global oil supply fell further because of sanctions on Iran.
OPEC and its allies have since last year been participating in a pact to cut output by 1.8 million bpd. The measure had helped rebalance the market in the past 18 months and lifted oil to around $75 per barrel from as low as $27 in 2016.
But unexpected outages in Venezuela, Libya and Angola have effectively brought supply cuts to around 2.8 million bpd in recent months.
Falih has warned the world could face a supply deficit of up to 1.8 million bpd in the second half of 2018.
“Both Saudi and Iran can show that they won,” an OPEC delegate said.
“Zanganeh can go back to his country and say ‘I won’, because we are keeping the original agreement unchanged. Falih can go back and say ‘we will be able to raise production to meet market needs’.”
The United States, which rivals Russia and Saudi Arabia for the position of world No.1 oil producer, is not participating in the supply pact.
With multilateralism under attack by populists and nationalists around the world, the recently approved $13 billion capital boost for the World Bank Group is a welcome development. But it will backfire politically unless the additional capital is used to mobilize more private-sector financing of global development goals.
PARIS – In April, governments from around the world agreed to a $13 billion capital increase for the World Bank Group, sending a clear signal that multilateralism is far from dead. The additional funding will strengthen the WBG’s capacity to support development projects around the world. But it also raises critical questions about how best to deploy the new funds and raise public capital in the future.
Meeting the 2030 United Nations Sustainable Development Goals(SDGs), as well as the WBG’s own goal of taking development finance from “from billions to trillions,” requires maximizing the potential of the latest capital increase. And to do that will require building a new architecture for development finance, so that a multitude of actors operating with limited resources have incentives to optimize performance, pursue joint action, and avoid duplicating one another’s efforts.
A new framework will force all stakeholders – including the WBG, regional development banks, bilateral agencies, the European Investment Bank (EIB), and other institutions – to reexamine their role in the larger system. We know from past experience that by strengthening the WBG, the use of public and private capital in development finance could become more fragmented. To avoid that outcome, we need a system that motivates diverse parties to work together transparently.
A key focus should be on reinforcing the “billions-to-trillions” approach, which focuses on mobilizing private-sector capital and ensuring the best use of public-sector capital. Accordingly, the increase in public money must not be allowed to deter private-sector contributions through hidden competition or a “crowding out” effect. Addressing these concerns will require a more clearly defined division of labor when it comes to allocating risks and responsibilities.
Moreover, it is time to rethink official development assistance (aid from governments), which remains crucial for alleviating poverty, protecting human dignity, and financing basic services for people in places where no other financial resources are available. Owing to limited investment in the SDGs, ODA must be deployed in such a way that it attracts additional financing, or channels existing resources through blended-finance (public-private) mechanisms.
As majority shareholders in the multilateral development-bank system, the largest contributors of ODA have a key role to play in aligning public- and private-sector incentives. By coming together, they can steer the international community toward a system based on shared goals and collective responsibility.
The WBG’s capital increase offers reassurance at a critical moment for multilateralism. But it should not be treated as an excuse to stop innovating, or to take the easy route of relying solely on public capital, while avoiding the difficult task of pursuing blended-finance approaches. Rather, we must seize the moment to address the sources of fragility, conflict, and violence around the world, and to create an encouraging environment for more private-sector investment. Only by maintaining the current momentum can we move the SDG agenda forward.
Until now, blended-finance mechanisms for mobilizing private capital have been used mostly in relatively stable middle-income countries. According to a recent OECD study, nearly 43% of the private finance raised by such mechanisms between 2012 and 2015 was used in upper-middle-income countries, while only 7% was put to work in the least-developed countries.
It is vitally important to expand the use of blended finance in fragile and low-income countries. Development banks’ private-sector arms will need to do more to target their capital outlays in ways that mitigate risk and attract private-sector capital, rather than inadvertently crowding it out.
The world is just a few years into the SDG agenda. But it is already clear that achieving it will require new incentives for public and private actors to direct investments toward those who are at risk of being left behind. That means creating a system in which public funds are consistently targeted at the right areas, and for the right purposes.
At a time of populist agitation against multilateral institutions, the WBG’s capital increase is a notable achievement in itself. But the current political environment makes it all the more important that we get the next phase of development finance right. We must stay focused on building and maintaining a cohesive architecture for meeting the SDGs and other international commitments, such as those embodied in the Paris climate agreement.
Change will not happen on its own. So, rather than being at the mercy of global financial flows, we must harness finance as a tool for achieving our goals. Doing so will require genuine, long-term engagement on the part of “shareholders,” and pressure from engaged citizens the world over.
The climate crisis we now face is a reflection of a broader crisis: a global confusion of means and ends.
We continue to use fossil fuels because we can (means), not because they are good for us (ends). This confusion is why Pope Francis and Ecumenical Patriarch Bartholomew are spurring us to think deeply about what is truly good for humanity, and how to attain it.
Earlier this month, the Pope and patriarch each convened business, scientific, and academic leaders, in Rome and Athens, respectively, to hasten the transition from fossil fuels to safe renewable energy.
In most of the world today, the purposes of politics, economics, and technology have been debased.
Politics is regarded as a no-holds-barred fight for power, economics as a ruthless scramble for wealth, and technology as the magic elixir for more economic growth.
In truth, according to Francis and Bartholomew, we need politics, economics, and technology to serve a far greater purpose than power, wealth, or economic growth.
We need them to promote human well-being today and for future generations.
America may be the most confused of all.
The United States today is rich beyond imagining, with median household income and gross domestic product per capita each equal to nearly $60,000.
The US could have it all.
Instead, what it has is widening income inequality, falling life expectancy, a rising suicide rate, and epidemics of obesity, opioid overdoses, school shootings, depressive disorders, and other grave ills.
The US incurred $300bn in losses from climate-related disasters last year, including three massive hurricanes – the frequency and intensity of which has risen, owing to fossil-fuel dependence.
The US has vast power, wealth, and growth, and yet diminished well-being.
The US economy and politics are in the hands of corporate lobbies, including Big Oil.
Resources are relentlessly allocated to developing more oil and gas fields not because they are good for America or the world, but because the shareholders and managers of ExxonMobil, Chevron, Conoco Philipps, and others demand it.
Trump and his minions work daily to undermine global agreements and domestic regulations that have been put in place to accelerate the shift from fossil fuels to renewable energy.
Yes, we can produce more oil, coal, and gas.
But for what? Not for our safety: the hazards of global warming are already upon us.
Not because we lack alternatives: the US has ample wind, solar, hydro, and other sources of primary energy that don’t cause global warming.
The US economy, alas, is an out-of-control juggernaut, chasing oil wealth and jeopardising our very survival.
Of course the US is not alone in the mad pursuit of wealth over well-being.
The same get-rich-quick confusion of means and ends is causing Argentina, host of the G20 Summit later this year, to pursue fracking of natural gas, with all the associated climate and environmental risks, instead of tapping its bounteous potential in wind, solar, and hydro power.
The same corruption of purpose is causing the Canadian government to guarantee a new pipeline to export output from its polluting and expensive oil sands to Asia, while under-investing in Canada’s vast renewable energy sources.
In his meeting with the CEOs of major oil and gas companies, Francis told them, “Our desire to ensure energy for all must not lead to the undesired effect of a spiral of extreme climate changes due to a catastrophic rise in global temperatures, harsher environments, and increased levels of poverty.” He noted that the oil companies are engaged in “the continued search for new fossil fuel reserves, whereas the Paris Agreement clearly urged keeping most fossil fuels underground.” And he reminded the executives that, “Civilisation requires energy, but energy use must not destroy civilisation!”
Francis underscored the moral dimension of the problem:
“The transition to accessible and clean energy is a duty that we owe toward millions of our brothers and sisters around the world, poorer countries and generations yet to come.
Decisive progress on this path cannot be made without an increased awareness that all of us are part of one human family, united by bonds of fraternity and solidarity.
Only by thinking and acting with constant concern for this underlying unity that overrides all differences, only by cultivating a sense of universal intergenerational solidarity, can we set out really and resolutely on the road ahead.”
As Francis was meeting the CEOs in Rome last week, Bartholomew was similarly convening leaders of scientific institutions, UN agencies, and major faiths in Athens and the Peloponnese, to chart a path to environmental safety.
Bartholomew also underscored the fundamental moral concern. “The identity of every society and measure of every culture are not judged by the degree of technological development, economic growth or public infrastructure,” he said.“Our civil life and civilisation are defined and judged primarily by our respect for the dignity of humanity and integrity of nature.”
The 300mn faithful of the Eastern churches led by the Ecumenical Patriarch are in lands facing extreme dangers from global warming: intense heat waves, rising sea levels, and increasingly severe droughts.
The Mediterranean region is already beset by environmental distress and forced migration from conflict zones.
Unchecked climate change – which has already contributed to conflict – would spell disaster for the region.
Bartholomew’s conference opened at the Acropolis, the very heart of ancient Athens, where 2,300 years ago Aristotle defined ethics and politics as the quest for well-being.
The political community, wrote Aristotle, should aim “at the highest good,” to be achieved by cultivating the virtues of the citizenry.
Aristotle famously contrasted two types of knowledge: techne (technical know-how) and phronesis (practical wisdom). Scientists and engineers have given us the technical knowledge to move rapidly from fossil fuels to zero-carbon energy.
Francis and Bartholomew urge us to find the phronesis, the practical wisdom, to redirect our politics and economies toward the common good. – Project Syndicate
*Jeffrey D Sachs, Professor of Sustainable Development and Professor of Health Policy and Management at Columbia University, is Director of Columbia’s Center for Sustainable Development and the UN Sustainable Development Solutions Network.
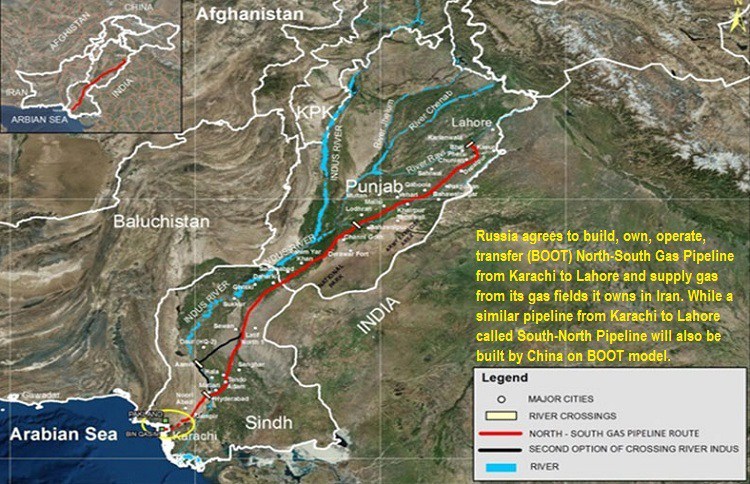
ISLAMABAD: In a major breakthrough, Pakistan and Russia are poised to sign a $10-billion offshore gas pipeline deal, a project planned by the latter to capture the energy market of Pakistan.
Sources told a local newspaper that the cabinet had approved the signing of the gas pipeline laying deal and Pakistan ambassador to Russia had been authorised to ink a memorandum of understanding with Moscow.
The envoy is likely to ink the understanding in Moscow on Monday. Final cost of the project will be assessed following a feasibility study to be conducted by Russian energy giant Gazprom.
Russia has nominated Public Joint Stock Company Gazprom for implementation of the project. Pakistan’s cabinet has also permitted the company to conduct the feasibility study at its own cost and risk.
Inter State Gas Systems (ISGS) – a state-owned company of Pakistan established to handle gas import projects and is already working on gas pipeline schemes like Tapi, has been nominated by Pakistan to execute the offshore pipeline project along with Gazprom.
ISGS is also working on the $10-billion Turkmenistan, Afghanistan, Pakistan and India (Tapi) gas pipeline to connect South and Central Asia and construction work on the scheme in Pakistan will start in March next year.
These projects are called a game changer for Pakistan as they will not only lead to regional connectivity, but will also meet growing energy needs of the country.
Amid a long-running tussle with Europe and the United States over the annexation of Ukrainian region of Crimea, Russia is looking for alternative markets and wants to capitalise on the growing energy demand in South Asia.
Russia, which controls and manages huge gas reserves in energy-rich Iran, plans to export gas by laying an offshore pipeline through Gwadar Port to Pakistan and India, which are seen as alternative markets because Moscow fears it may lose energy consumers in Europe over the Crimea stand-off.
Russia has been a big gas exporter to European Union (EU) countries and Turkey since long and despite US anger the European bloc has continued to make imports to meet its energy needs.
Moscow receives gas from Turkmenistan and then exports it to EU states. Later, it has got gas deposits in Iran as well and is looking to gain a foothold in markets of Pakistan and India.
Pakistan has been experiencing gas shortages, particularly in winter, for the past many years as domestic production has stood static with new additions being offset by depleting old deposits.
In a bid to tackle the crisis, the previous government of Pakistan Muslim League-Nawaz (PML-N) kicked off liquefied natural gas (LNG) imports from Qatar under a 15-year agreement two and a half years ago and is bringing supplies through other sources as well.
According to a government official, after signing the MoU for the offshore pipeline, work on the feasibility study will begin in an attempt to assess viability of the project. Russia is even ready to finance the study. Russian gas exports touched an all-time high in 2017.
According to Gazprom, gas flows to Europe and Turkey, excluding ex-Soviet states, hit a new daily record at 621.8 million cubic metres.
Annual exports touched 179.3 billion cubic metres (bcm) in 2016, a significant jump from the previous high of 161.5 bcm in 2013 and well above the 2015 total of 158.6 bcm.
Iyad el-Baghdadi is president of the Kawaakibi Foundation, a nonprofit organization focused on the future of liberty in the Muslim world.
It’s been two years since Saudi Arabia’s Crown Prince Mohammed bin Salman announced a national transformation project to structurally overhaul the Saudi state. His “Vision 2030” reform program aims to change the kingdom into a “normal country,” with a post-oil economy and a post-Wahhabi Islam.
Economic reform is the driver behind Vision 2030 – the International Monetary Fund has warned that Saudi Arabia will run out of cash without serious structural reform – but other reforms are no less important. Increasing labor participation by women, for example, requires lifting such restrictions as the driving ban (which is set to end on June 24).
Perhaps the most head-turning change is the transition away from Wahhabism, the arch-conservative version of Islam that had long been allied with the Saudi state. The government has recently stopped all funding to Wahhabi institutions outside Saudi Arabia and severely curtailed the powers of the religious police. Curbing the Wahhabis is great news for everyone. They are extremist, regressive, sectarian, and had received Saudi state support to spread their ideology across the globe, often to destructive effect.
The rest of the international community has a direct stake in the success of Saudi Arabia’s reform effort. Should Vision 2030 fail, we’ll be facing an explosion of instability at the very heart of the Arab and Muslim world. Unfortunately, the 32-year-old in charge of Vision 2030 – Mohammed bin Salman himself – has become a threat to his own project.
Vision 2030 represents, at its core, a new Saudi social contract. But the way the crown prince is rewriting this contract should give us pause.
The Saudi system of governance prior to his rise could be described as a consultative authoritarianism. The king would seek and receive advice from senior members of the royal family, as well as trusted court advisers. In a series of drastic steps, including the roundup of rival princes, the crown prince has effectively dismantled the old structure. Saudi Arabia is now the absolute monarchy that it wasn’t under King Abdullah, King Fahd or any of their predecessors.
Some have argued that serious reform would be impossible without a consolidation of power. But the crown prince’s efforts have gone from the decisive to the destabilizing. His recent shakedown of leading business figures had nothing to do with the rule of law and may have spooked investors. Recent figures show that foreign direct investment hit a 14-year low in Saudi Arabia last year (compared to an 8 percent rise in the neighboring United Arab Emirates).
In any case, the crown prince should have done away with the old system by allowing citizens space to have a say in the new Saudi Arabia that he is envisioning for them – allowing them to co-sign their new social contract. He is doing precisely the opposite.
Among those arrested so far is Essam Al Zamel, a young economist who ran the figures on Vision 2030 and offered criticisms and suggestions for improving it. Recent reports indicate he is being set up for serious charges that would justify long-term imprisonment.
He has also arrested moderate religious figures, including the young intellectual Abdullah Al Maliki, and ex-Wahhabi Muslim reformer Hassan Farhan Al Maliki. These figures could be effective advocates for religious reform, but instead they are facing charges that could put them away for a long time, alienating their support base.
Most recently, the crown prince has arrested Saudi Arabia’s leading women’s rights activists – including Loujain Al Hathloul, Eman Al Nafjan, and Aziza Al Yousuf – charging them with treason. These women have a long history of advocating for social reforms. But the government has treated them like threats instead of potential allies.
In short, the crown prince is promising economic reform while imprisoning economic reformers; he’s promising religious reform while imprisoning religious reformers; he’s promising social reform while imprisoning leading feminists. As he silences the once dynamic Saudi public sphere, note how these voices are being replaced: thousands of bots are flooding Saudi social media, many with pictures of the crown prince, cheering his every move.
The decision-making of the world’s largest oil exporter is now in the hand of a small number of individuals with no consultative process in place, and with dissenters immediately jailed.
Many of the crown prince’s big moves have deteriorated into protracted wars of attrition, such as the war in Yemen or the feud with Qatar. His mass arrest of the leading women’s rights activists is another potential quagmire.
Not only does it quite rightly tarnish his image among the global women’s rights community (in the age of #MeToo, no less), but it also threatens his economic reform agenda, considering that the crown prince’s ordered the detentions after a high-profile visit to the United States in which he met leading celebrities and business leaders. A war of attrition with the global women’s rights movement is not one that he is likely to win, despite his huge PR budget.
The crown prince should release the women’s rights activists, drop all charges against them, and allow them to continue their careers freely. That would be the best way to reassure the world that the reforms are real and remain on track.
For the sake of global stability, Saudi reforms need to be saved from Mohammed bin Salman’s absolutism and heavy-handedness. History shows that governments with no tolerance for dissent usually end up creating disasters.





PARIS – In April, governments from around the world agreed to a $13 billion capital increase for the World Bank Group, sending a clear signal that multilateralism is far from dead. The additional funding will strengthen the WBG’s capacity to support development projects around the world. But it also raises critical questions about how best to deploy the new funds and raise public capital in the future.
Meeting the 2030 United Nations Sustainable Development Goals(SDGs), as well as the WBG’s own goal of taking development finance from “from billions to trillions,” requires maximizing the potential of the latest capital increase. And to do that will require building a new architecture for development finance, so that a multitude of actors operating with limited resources have incentives to optimize performance, pursue joint action, and avoid duplicating one another’s efforts.
A new framework will force all stakeholders – including the WBG, regional development banks, bilateral agencies, the European Investment Bank (EIB), and other institutions – to reexamine their role in the larger system. We know from past experience that by strengthening the WBG, the use of public and private capital in development finance could become more fragmented. To avoid that outcome, we need a system that motivates diverse parties to work together transparently.
A key focus should be on reinforcing the “billions-to-trillions” approach, which focuses on mobilizing private-sector capital and ensuring the best use of public-sector capital. Accordingly, the increase in public money must not be allowed to deter private-sector contributions through hidden competition or a “crowding out” effect. Addressing these concerns will require a more clearly defined division of labor when it comes to allocating risks and responsibilities.
Moreover, it is time to rethink official development assistance (aid from governments), which remains crucial for alleviating poverty, protecting human dignity, and financing basic services for people in places where no other financial resources are available. Owing to limited investment in the SDGs, ODA must be deployed in such a way that it attracts additional financing, or channels existing resources through blended-finance (public-private) mechanisms.
As majority shareholders in the multilateral development-bank system, the largest contributors of ODA have a key role to play in aligning public- and private-sector incentives. By coming together, they can steer the international community toward a system based on shared goals and collective responsibility.
The WBG’s capital increase offers reassurance at a critical moment for multilateralism. But it should not be treated as an excuse to stop innovating, or to take the easy route of relying solely on public capital, while avoiding the difficult task of pursuing blended-finance approaches. Rather, we must seize the moment to address the sources of fragility, conflict, and violence around the world, and to create an encouraging environment for more private-sector investment. Only by maintaining the current momentum can we move the SDG agenda forward.
Until now, blended-finance mechanisms for mobilizing private capital have been used mostly in relatively stable middle-income countries. According to a recent OECD study, nearly 43% of the private finance raised by such mechanisms between 2012 and 2015 was used in upper-middle-income countries, while only 7% was put to work in the least-developed countries.
It is vitally important to expand the use of blended finance in fragile and low-income countries. Development banks’ private-sector arms will need to do more to target their capital outlays in ways that mitigate risk and attract private-sector capital, rather than inadvertently crowding it out.
The world is just a few years into the SDG agenda. But it is already clear that achieving it will require new incentives for public and private actors to direct investments toward those who are at risk of being left behind. That means creating a system in which public funds are consistently targeted at the right areas, and for the right purposes.
At a time of populist agitation against multilateral institutions, the WBG’s capital increase is a notable achievement in itself. But the current political environment makes it all the more important that we get the next phase of development finance right. We must stay focused on building and maintaining a cohesive architecture for meeting the SDGs and other international commitments, such as those embodied in the Paris climate agreement.
Change will not happen on its own. So, rather than being at the mercy of global financial flows, we must harness finance as a tool for achieving our goals. Doing so will require genuine, long-term engagement on the part of “shareholders,” and pressure from engaged citizens the world over.